SENIOR LIVING COSTS, EXPLAINED
Senior Living Costs and Payment Options
Real numbers and honest answers about what assisted living and memory care cost, what Medicare and Medicaid actually cover, and how families in St. Charles, Geneva, Batavia, and the western suburbs plan for the cost of care.
What Senior Living Really Costs
Senior living costs vary widely depending on the level of care, location, and community—but most families are surprised to learn that neither Medicare nor most private health insurance covers ongoing assisted living or memory care. Understanding what's actually included in a monthly fee, and what funding sources may help, is often the first step before comparing specific communities.
"The earlier a family understands the real cost picture, the more options they have. Waiting until money is the crisis point limits choices." — Brad Esposito
Families throughout St. Charles, Geneva, Batavia, and the greater Tri-Cities area often start planning for cost long before they're ready to tour a community—and for good reason. The questions below cover what we're asked most often about pricing, payment options, and what happens if funds run low. For another Fox Valley-area price picture, see our Naperville cost guide.
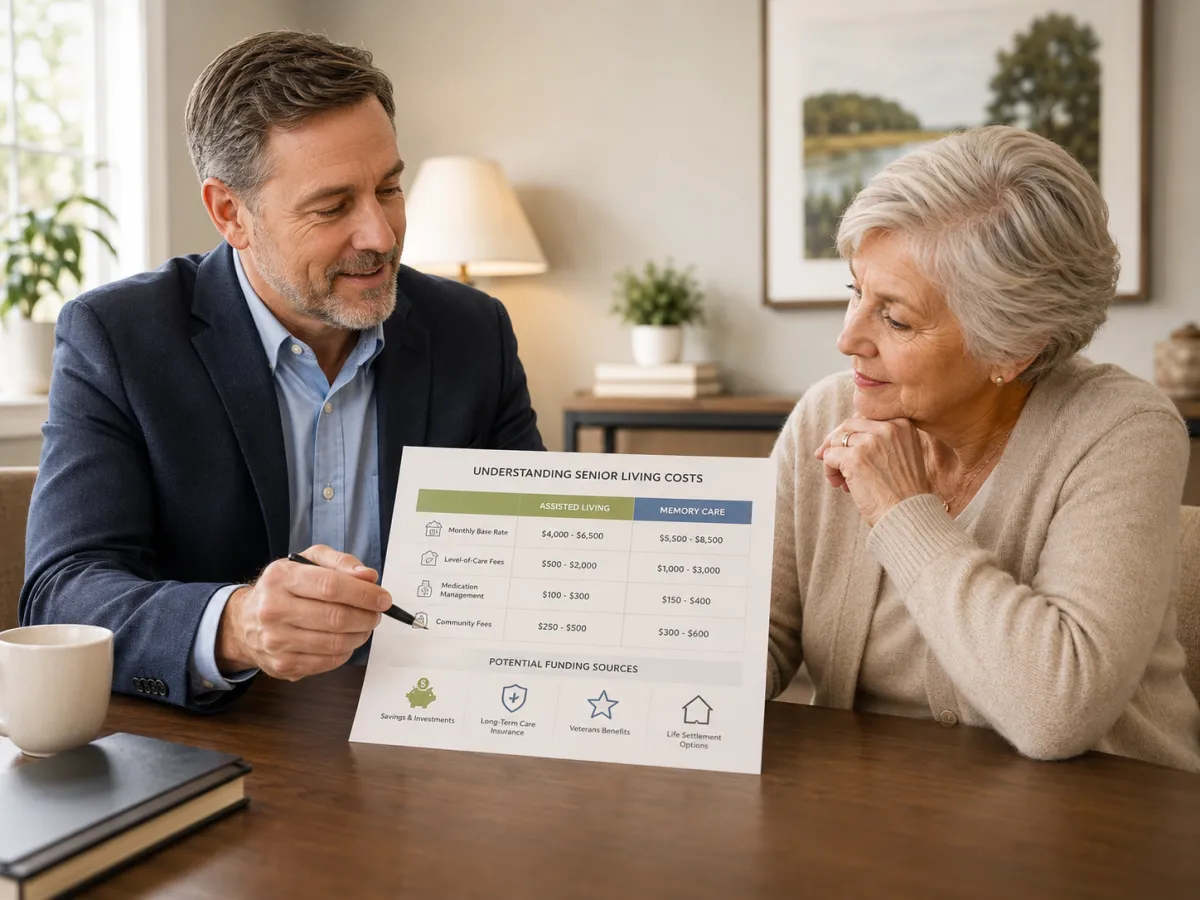
Monthly base rate (room, meals, standard care)
Level-of-care fees (added as needs increase)
Medication management fees
Community fees and move-in deposits
Funding sources: private pay, long-term care insurance, VA Aid and Attendance, Medicaid/supportive living
Senior Living Costs and Payment Options
How much does assisted living cost near Geneva, St. Charles, Batavia, and Aurora?
There is no single assisted living price.
The cost depends on the city, apartment, community, care level, medication assistance, number of caregivers needed, and additional services.
Costs vary a lot by community, apartment size and care level. Ask each community for its base rate, what's included, and how care charges are set, in writing. Actual pricing near Geneva, St. Charles, Batavia, North Aurora, Aurora, Elgin, Naperville, and nearby suburbs may be lower or considerably higher.
The better question is:
What will the total monthly cost be after my parent’s actual care needs are included?
Always request a written estimate that includes base rent, care, medication fees, community fees, and likely future increases.
How much does memory care cost near Geneva, St. Charles, Batavia, or Naperville?
Memory care generally costs more than traditional assisted living because residents often need increased supervision, dementia-trained staff, structured programming, and a secured environment.
Pricing varies significantly by community, apartment, care level, location, and the amount of hands-on help required.
When comparing memory care, ask for the total expected monthly cost—not only the advertised starting rate.
Also ask whether care is priced by levels, points, or an all-inclusive model and what happens financially if behaviors, nighttime needs, incontinence, or mobility support increase.
What is normally included in the monthly senior living fee?
The base monthly fee may include the apartment, meals, housekeeping, activities, transportation, basic utilities, and emergency response.
Additional fees may apply for:
Medication management
Bathing and dressing
Toileting
Incontinence care
Escorts
Transfers
Nighttime checks
Additional laundry
Higher levels of care
Transportation
Community or move-in fees
Cable, phone, or internet
Ask for a written breakdown of current charges and an explanation of how future care increases are calculated.
A low starting price is not necessarily a low total price.
Does Medicare pay for assisted living or memory care?
Generally, no.
Medicare does not usually pay for the ongoing room, meals, supervision, and personal-care costs of assisted living or memory care.
Medicare may still cover qualifying medical services such as physician visits, therapy, hospice, medical equipment, or certain home health services while someone lives in a senior community.
Those benefits are separate from paying the monthly senior living bill.
Medicare states that it generally does not cover non-medical long-term or custodial care, whether it is provided at home, in assisted living, or in a nursing home.
Does Medicaid pay for assisted living in Illinois?
Illinois Medicaid generally does not pay the full monthly bill at an ordinary private-pay assisted living community.
However, qualifying individuals may receive services through the Illinois Supportive Living Program.
Medicaid may also help pay for long-term nursing home care when the person meets medical and financial eligibility requirements.
The word “Medicaid” can refer to several different programs and care settings. Families should avoid assuming that approval for one Medicaid benefit automatically means a particular assisted living community will be covered.
The first step is identifying the correct care setting and eligibility pathway.
Does Medicaid pay for room and board in Illinois supportive living?
Medicaid helps pay for qualifying supportive-living services, but the resident remains responsible for the room-and-board portion.
Residents typically contribute available income toward lodging, meals, and services while retaining a personal-needs allowance under program rules.
The exact amount depends on the person’s income, eligibility, and current program requirements.
Illinois specifically states that the resident is responsible for room and board, while the waiver supports qualifying personal care and other services.
Does long-term care insurance cover assisted living or memory care?
Many long-term care insurance policies cover assisted living and memory care, but it depends on the policy. Most require proof that the person needs help with a set number of daily tasks or has memory loss, and many have a waiting period before benefits start. Call the insurer and ask about the benefit triggers, the daily or monthly maximum and the waiting period. Ask which forms the community must fill out. Starting early helps avoid surprises at move-in.
Learn more: Paying for senior care in Illinois (https://ilseniorsource.com/post/paying-for-senior-care-illinois)
Can VA Aid and Attendance help pay for assisted living?
Possibly.
VA Aid and Attendance may provide additional monthly pension payments to qualifying Veterans and surviving spouses who need help with daily activities or meet other eligibility requirements.
It is not automatic, and eligibility may depend on wartime service, care needs, income, net worth, medical expenses, marital status, and other factors.
The benefit is generally added to an eligible VA pension rather than paid directly to a senior living community.
Families should work with a qualified and properly accredited resource when evaluating or applying for VA benefits.
What happens when someone begins running out of money in assisted living?
Begin planning as soon as the concern becomes visible.
Do not wait until only one or two months of funds remain.
Possible paths may include:
Reviewing long-term care insurance
Evaluating VA benefit eligibility
Selling or using equity from a home
Considering a lower-cost apartment
Exploring Illinois supportive living
Determining whether Medicaid nursing care may eventually be needed
Speaking with an elder law attorney
Reviewing family support realistically
Ask the community whether it has a Medicaid pathway, financial hardship policy, or another affiliated setting.
A promise that “we will figure it out later” should not replace a written financial plan.
How do we compare communities that price care in different ways?
Some communities charge care by levels, some by points, and some include most care in one rate. To compare them, ask each one for the full monthly total for your parent's actual needs today. Then ask what that total would be if needs went up one step, such as help with bathing or more medicine help. Compare those two totals side by side.
Learn more: How much senior living costs in Illinois
For a step-by-step worksheet, read our guide on how to compare senior living costs.
Why can the monthly cost of assisted living change after move-in?
Most assisted living communities charge a base rate for the apartment, meals and basic services, plus care charges based on how much help a resident needs. Before move-in, a nurse usually does an assessment that sets the starting care level. As needs change, a new assessment can raise or lower the care charge. Ask how care levels are priced, what triggers a new assessment, how much notice you get before an increase, and how often base rates have gone up.
Learn more: How much senior living costs in Illinois
How to read the senior living prices you see
How should we read the senior living prices we see online?
Treat them as a rough starting range, not a quote. Directory averages often reflect a starting rent before care charges are added. Statewide averages describe the whole state, not one town or your parent's care needs. Use these numbers to set expectations, then get written prices from the communities you are considering.
Learn more: How much senior living costs in Illinois
What should a written price quote from a community include?
Ask for it line by line: the monthly base rate for the apartment, the care charge for your parent's assessed needs, any one-time community or move-in fee, and anything billed separately, such as medication management, incontinence supplies or a second-person fee. Ask how long the quote is good for. Having every quote in the same written format makes it much easier to compare communities fairly.
Learn more: Paying for senior care in Illinois


quicklinks
Get in touch
Senior Source - Senior Living Advisors
200 W River Dr
St. Charles IL 60174
Monday-Friday: 8am-4:00pm
Weekends by Appointment
Subscribe to our Newsletter
Learn more about what's happening in our local area. Events, Activities, and Resources
© 2026 Senior Source LLC Copyright. All rights reserved